Real Business Is in Policy (Part I)
Policy cultivates markets. Lived practice decides whether they work.
Main argument. The largest business opportunities often form when policy sets rules, redirects money and exposes unmet needs, before customers buy.
On this page
- Business Begins Before the Customer Buys
- Every Market Has Rules
- Five Ways Policy Creates Demand
- Case Studies
- Intention and Implementation
- People Show Us What Really Works
- Build with People
- Software as Institutional Design
- Entrepreneurship Versus Capture
- When the Argument Breaks
- What This Means
- Return to the Payment
- Sources
Editorial illustration. At a market stall, two people complete a mobile payment beneath a teal canopy. Around them, four emblematic spheres represent Rules, Money, Technology and People, connected by luminous ribbons. The scene suggests that everyday commerce sits inside a wider architecture of rules, finance, systems and trust.
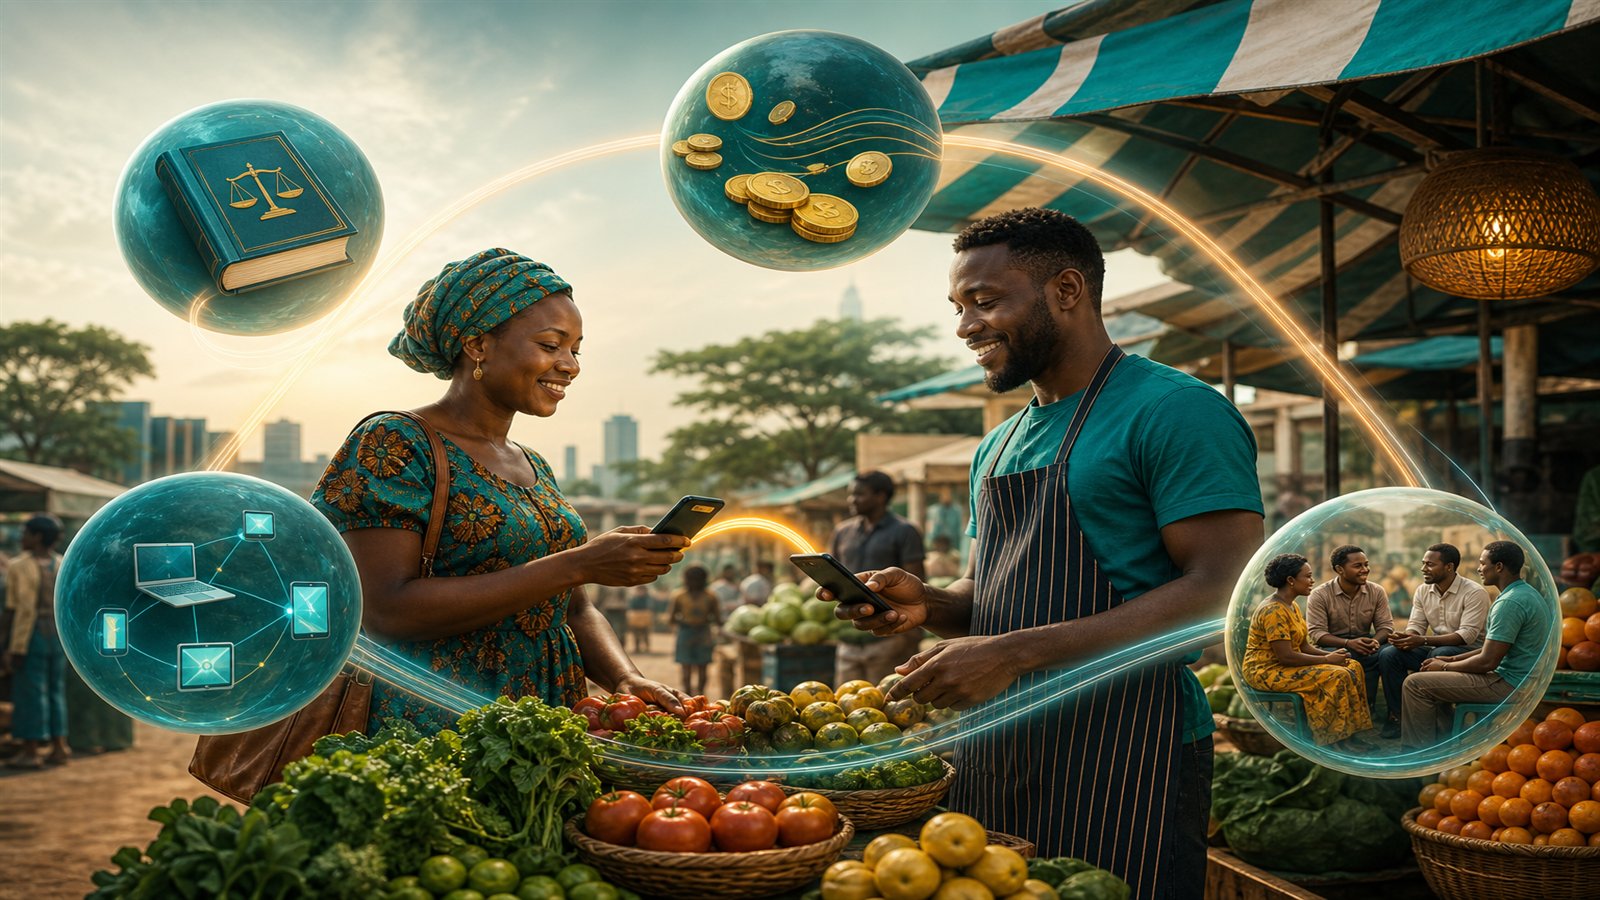
On an ordinary afternoon somewhere in an African town, a customer pays a small business owner through a mobile payment channel. To the customer, it is a simple gesture: tap, confirm, done. Goods change hands. Life continues.
Beneath that moment, however, sits another transaction, the one most people never see. Rules decide whose identity is accepted. Licensing decides who may offer the service. Authorisation decides whether the payment can move. Taxation, settlement, consumer protection and record keeping all ride quietly on the same few seconds of convenience.
Technology did not invent that moment alone. It works because institutions, standards and trusted systems make it possible. The payment looks personal. The architecture beneath it is public.
This is why I argue that real business is in policy.
I do not mean political patronage. I do not mean bribery. I do not mean lobbying for private privilege dressed up as public interest. My argument is economic, not partisan. Markets are cultivated spaces. Laws, regulations, standards, public budgets, licences, incentives, infrastructure and institutional trust help decide whether those markets exist, who may enter them, how money moves, what behaviour is required and who bears the risk.
A business may sell inside a market. Policy helps determine whether that market is worth entering at all.
Business Begins Before the Customer Buys
Most entrepreneurs are trained to study products, customers, prices, competition and profit. That work still matters. Customers remain the final judges of value. Cash flow remains the discipline that separates ambition from survival.
I increasingly see another layer beneath all this.
The deeper analysis also examines laws and regulations, public budgets, licences, standards, tax incentives, procurement, infrastructure and institutional priorities. These are not footnotes to strategy. They are often the conditions under which strategy becomes possible.
The ordinary entrepreneur asks where customers are spending money today. The policy-aware entrepreneur also asks where institutions have decided money must, should or may begin to flow.
When a ministry expands school feeding, demand for logistics, packaging, nutrition tracking and local supply chains shifts. When a central bank clarifies who may issue e-money, who may act as an agent, and how customer funds must be safeguarded, as Kenya’s mobile-money rules did over successive rounds, payment products, float management and merchant tools become bankable businesses rather than regulatory experiments. When a city enforces building standards, the market for safer materials and skilled inspection grows, or shrinks, if enforcement never arrives.
Customers reveal preference. Policy often redirects possibility.
Every Market Has Rules
No market is a pure open field. Every market has rules, written and unwritten.
Policy influences who can enter a market and what businesses must do once they are inside. It shapes how customers are protected, how money moves, how risks are shared, what information must be reported and what conduct is prohibited. It also decides which activities receive support through credit guarantees, tax relief, training programmes or public contracts.
Rules can create markets. They can expand them. They can formalise what once lived only in informal networks. They can restrict harmful practice. They can also destroy fragile livelihoods when design is careless or enforcement is selective.
That is why treating “the market” as if it were separate from “the state” is often incomplete. Governments, regulators, councils, development agencies, industry bodies and courts are not one uniform actor. They pull in different directions. But together they help set the stage on which private enterprise performs.
Five Ways Policy Creates Demand
If we strip away jargon, policy creates commercial demand in at least five practical ways.
1. Permission
Policy allows an activity that was previously prohibited, uncertain or unrecognised. When digital signatures become legally valid, software that creates and stores them becomes useful. When community health workers receive formal recognition, tools that support their work stop being experimental and start being necessary.
2. Obligation
Policy requires businesses or citizens to do something. Obligation creates demand for compliance solutions: bookkeeping that meets tax rules, waste handling that meets environmental standards, accessibility features that meet public service requirements. The cost of ignoring the rule becomes higher than the cost of solving it.
3. Incentive
Tax relief, subsidies, grants or guarantees make adoption easier or less risky. Incentives do not invent need by themselves, but they change the timing and courage with which people act on need.
4. Procurement
Government or another institution becomes a buyer or financier. A school system that buys learning materials, a hospital network that buys diagnostics, or a county that contracts waste collection is not merely regulating, it is shaping demand through the purse. Local offtake rules, when real, can pull small processors into formal supply chains; when paper-only, they leave the same producers waiting at the gate.
5. Infrastructure
Shared systems such as payment rails, registries, standards and identity services enable private businesses to operate. Infrastructure lowers transaction costs, the friction of finding partners, verifying identity, moving money and enforcing agreements. When friction falls, more honest trade becomes possible.
These five mechanisms rarely appear alone. Permission without infrastructure can remain theoretical. Obligation without fair process can become harassment. Incentive without measurement can become waste. Procurement without transparency can become capture. The art is in the combination.
Case Studies: When the Mechanisms Become Real
Concepts travel farther when they are attached to named institutional facts. The three cases below are not exhaustive success stories. They are illustrations of how permission, procurement and obligation shape commercial demand, and where implementation gaps remain.
1. Kenya’s mobile-money rules: permission plus payment infrastructure
Kenya’s mobile-money market did not rest forever on informal forbearance. The National Payment System Act, 2011 created a statutory frame for payment systems and payment service providers. The National Payment System Regulations, 2014 then operationalised authorisation, oversight, designation of instruments and related consumer-protection duties. The Central Bank of Kenya summarises that mobile money operators are authorised as payment service providers under that Act and those Regulations, including categories such as electronic retail transfers and e-money issuance.
For enterprise, the lesson is structural. Once e-money issuance, agent arrangements and safeguarding expectations are written into the rulebook, merchant tools, float management, reconciliations and adjacent fintech products become bankable businesses rather than regulatory experiments. GSMA’s Mobile Money Regulatory Index likewise treats the 2011 Act and 2014 Regulations as Kenya’s formal legal framework for mobile money, after an earlier period of letters of no-objection.
Mechanism: Permission + Infrastructure. Gap that remains: rules can authorise a channel and still leave last-mile literacy, fraud fear, device sharing and uneven agent quality to be solved by product design and ethnography.
2. Home-grown school meals: procurement as a local market signal
Kenya’s National School Meals and Nutrition Strategy 2017-2022 frames school feeding as more than a nutrition transfer. It prioritises purchase from local smallholder farmers where practicable and states that food procurement for the national programme is guided by the Public Procurement and Asset Disposal Act, with preference for qualifying local smallholders. School-level home-grown modalities typically move cash to school accounts and use school meals committees to run competitive local tenders, creating demand for aggregation, quality assurance, storage, transport and compliant supplier documentation.
Independent programme reviews, including the 2024 Kenya school meals case study published via the London School of Hygiene & Tropical Medicine research repository, describe coexisting modalities (centralised in-kind, school-level cash, aggregator pilots) and the practical frictions of funding adequacy, storage and supplier capacity. That is the implementation gap in plain sight: the policy names a local market; delivery still depends on money arriving on time, committees that can tender fairly, and suppliers who can meet quality and documentation standards.
Mechanism: Procurement (+ Incentive for local offtake). Gap that remains: a school feeding circular without funded school accounts, storage or fair tendering does not create a durable market, only an announcement.
3. Data protection and digital credit: obligation as both market and gate
Kenya’s Data Protection Act, 2019 established rights for data subjects and duties for controllers and processors, with the Office of the Data Protection Commissioner as regulator. For digital lenders and related platforms, the ODPC’s Guidance Note for Digital Credit Providers clarifies expectations around transparency, security, subject-access requests, identity verification when disclosing personal data, registration and breach notification.
Obligation here creates honest commercial demand: privacy notices, consent tooling, access-request workflows, encryption, DPIAs and audit trails. It also encodes institutional design risks. If identity verification, language or device assumptions are too narrow, compliance systems can exclude the very users a financial-inclusion product claims to serve. The business opportunity is therefore double-edged: build tools that make lawful processing practical, and design so that protection does not become a new form of quiet exclusion.
Mechanism: Obligation. Gap that remains: paper compliance without usable appeals, plain-language notices or alternative verification paths can satisfy a checklist while failing lived legitimacy.
The Opportunity Between Intention and Implementation
I believe the opportunity is often found between policy intention and implementation capacity.
Editorial process illustration with five stations on a pathway: 1. People facing a problem. 2. A public goal or new rule. 3. A missing solution shown as a gap. 4. A business stepping onto the path. 5. People and business gaining together.
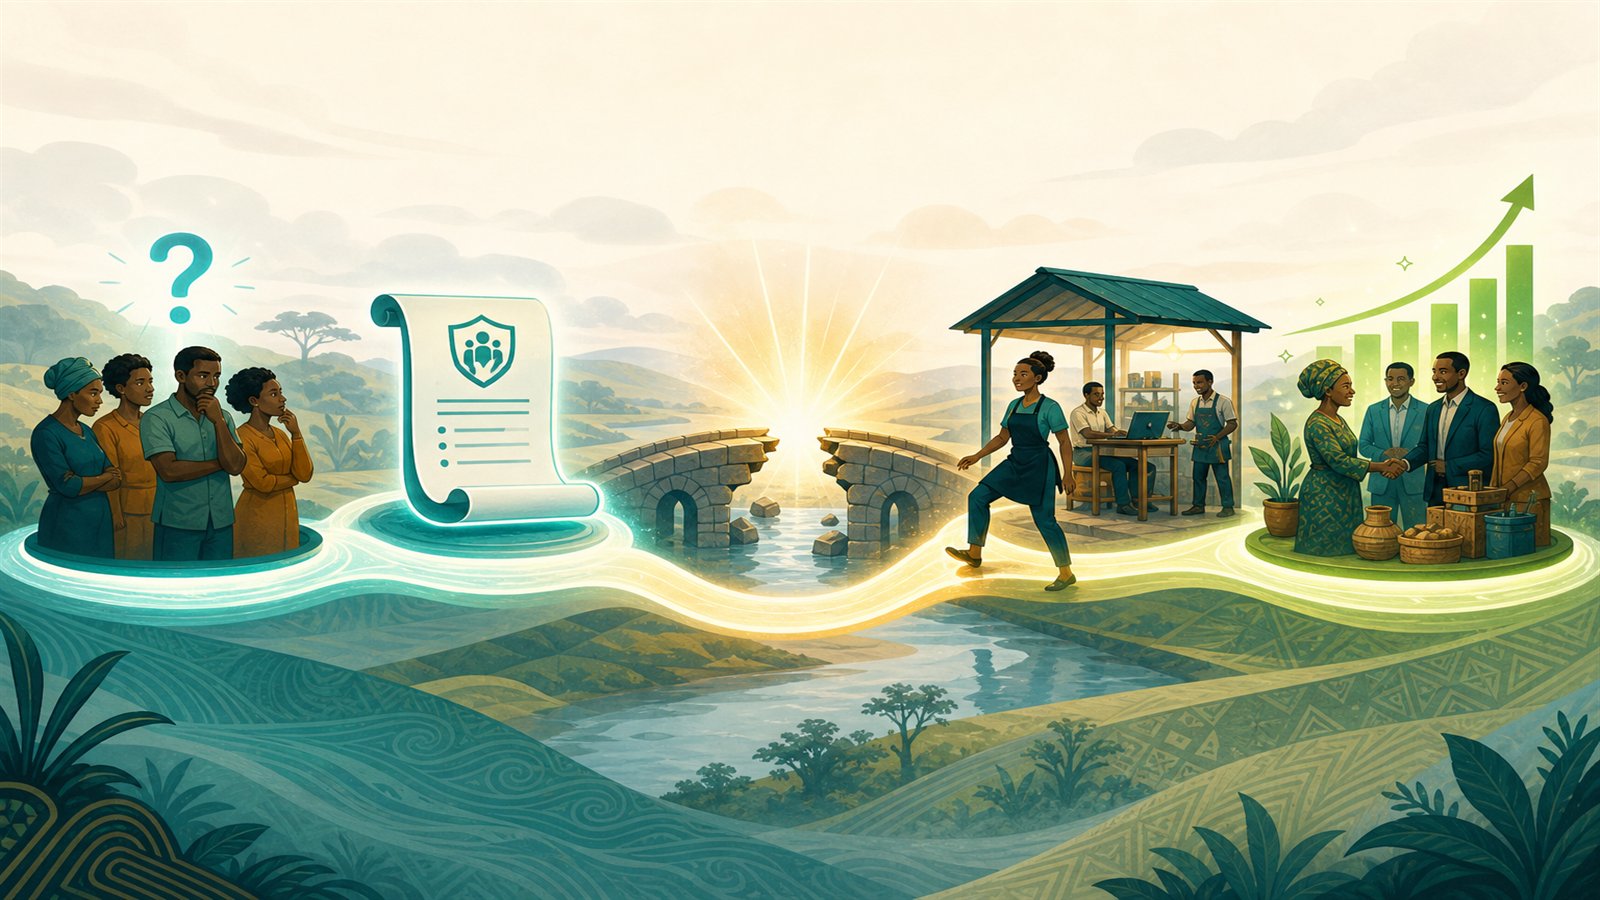
The journey is familiar across sectors. People experience a real problem, unsafe food, unpaid invoices, inaccessible credit, lost land records, unreliable transport. Government or another institution defines a public goal: safer markets, faster payments, broader inclusion, cleaner cities. Then a gap remains between the intention and delivery.
Institutions may have a mandate but lack technology, data, delivery channels, skills, financing, coordination, monitoring or public trust. A capable business builds the missing solution. The public gains. The business earns sustainable value.
The gap between institutional intention and implementation capacity is often where the real business opportunity lives.
This is not a call to wait for perfect policy. It is a call to notice where society has already named a destination and still lacks a reliable road.
People Show Us What Really Works
Policy is normally written from the top. Life is experienced from the ground.
Formal systems often assume that everyone has a smartphone, that connectivity is reliable, that people understand official language, that records are complete, that trust already exists and that price is always the main concern.
Lived reality is frequently different. Devices are shared. Records live in notebooks, memory and WhatsApp threads. Commerce runs on community trust networks as much as on contracts. Cash-flow pressure can outweigh long-term savings. Fear of fraud can block an elegant digital product. Workarounds become the real operating system.
Ethnography, simply put, careful observation of how people actually live and work, is therefore not an academic luxury. It is business intelligence. Good design begins by watching what people do on a busy Tuesday, not only what a policy paper or a business plan assumes they do.
Before you ship, ask: Where do workarounds cluster? Which step causes people to abandon the process? Whose ID, phone or language is assumed? Who is trusted to hold cash, float or records when the system fails? Those answers usually matter more than another feature request from the boardroom.
When we ignore lived practice, we build solutions that look compliant and feel unusable. When we honour lived practice, we discover the features that make policy intentions survive contact with daily life.
Build with People: Action Research
Action Research sounds technical. In practice it is a disciplined cycle of learning while doing.
- Observe the lived problem in the place it actually happens.
- Diagnose the real causes, not only the ones named in the policy brief.
- Design with the people affected, not merely for them.
- Test in a real setting with a clear success measure.
- Measure what changed for users and for the institution.
- Reflect, improve and decide whether to scale, revise or stop.
The point is not endless consultation. The point is to treat users as contributors to innovation, not merely recipients of someone else’s cleverness. A market woman who shows you why she rejects a digital receipt is not resisting progress. She is teaching you where trust breaks.
Businesses that learn this way build products that fit. Institutions that learn this way design rules that can be implemented. Communities that are invited into the cycle are more likely to defend what works.
Software as Institutional Design
Software increasingly turns policy into daily actions.
Registration decides who can enter. Permissions decide who has authority. Algorithms influence what becomes visible. Payment systems decide how money moves. Databases decide what is remembered. Appeals processes decide whether mistakes can be challenged.
Every digital system carries an implicit set of rules. In that sense, software is also institutional design.
That means developers, product managers and founders are not merely shipping features. They are encoding priorities. A form that requires a national ID that many people lack is a policy choice. A dashboard that makes complaints invisible is a policy choice. A settlement rule that favours one party’s cash flow over another’s is a policy choice, even when no politician signed it.
Diagnostic questions help: Does this form require an ID, phone number or literacy level many users lack? Can a rejected applicant see why and appeal? Whose metric appears first on the dashboard, the citizen’s outcome or the institution’s throughput? Where KYC or digital-ID rules tighten without alternative channels, whole segments of honest trade can be pushed back into cash and silence.
The ethical question is straightforward: do our systems expand fair participation, or do they quietly narrow it?
Policy Entrepreneurship Versus Policy Capture
Here the distinction matters most.
Policy entrepreneurship identifies a public problem, produces evidence, tests practical solutions, engages stakeholders transparently, creates measurable public value and earns sustainable commercial returns. It treats the rules as a field for responsible innovation.
Policy capture seeks privileged access, blocks fair competition, manipulates rules, protects a small group, transfers public value into private hands and avoids accountability. It treats the rules as a private enclosure.
Conceptual comparison. Left panel: Build value: open participation, evidence, trust and shared gain among many people. Right panel: Capture the rules: closed access, privilege, exclusion and concentrated private gain.
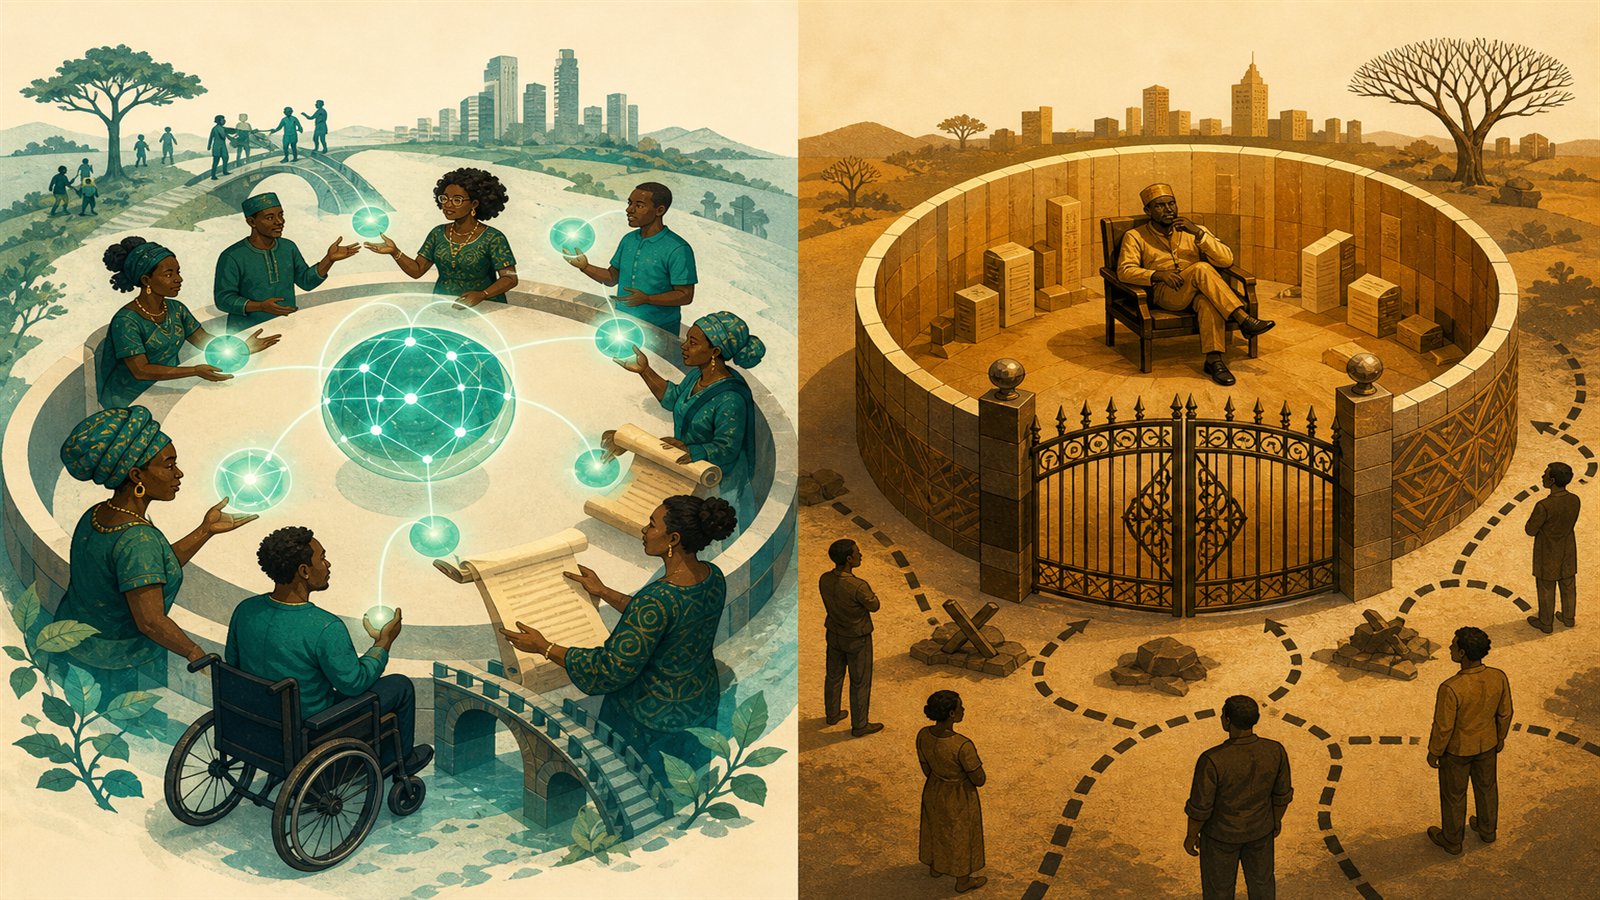
Good policy business creates value for many. Bad policy capture protects a privileged few.
My position is simple: build value, do not capture the rules. Policy should not be manipulated to eliminate competitors. Economic rents, extra profits that come from privileged access rather than better service, are not the same as earned returns from solving hard problems. One hollows out markets. The other deepens them.
When the Argument Breaks
No serious claim should be treated as absolute truth. The policy-to-business pathway has clear edge cases.
A policy announcement without funding may not create a real market. A regulation without enforcement may create compliance only on paper. A subsidy-dependent market may collapse when funding ends. A successful pilot may fail at scale. A licence may protect consumers, or merely protect incumbents. More technology does not automatically create inclusion. Legal compliance does not automatically create legitimacy. Policy uncertainty is a genuine business risk, not a detail for the footnotes.
These counter-examples do not cancel the argument. They discipline it. They remind us that opportunity is not the same as a press release, and that durable demand requires money, capacity, trust and follow-through.
What This Means for Every Business
Whether you run a stall, an advisory practice, a research team, a startup or an investment fund, four practical actions follow.
Four practical actions for every business. 1. Watch the rules, notice where laws, budgets, standards and institutional priorities are changing. 2. Find the gap, identify what people and institutions still cannot do. 3. Build with people, test the proposed solution with those who will use or experience it. 4. Prove the value, show that the solution saves money, builds trust, expands opportunity or improves lives.
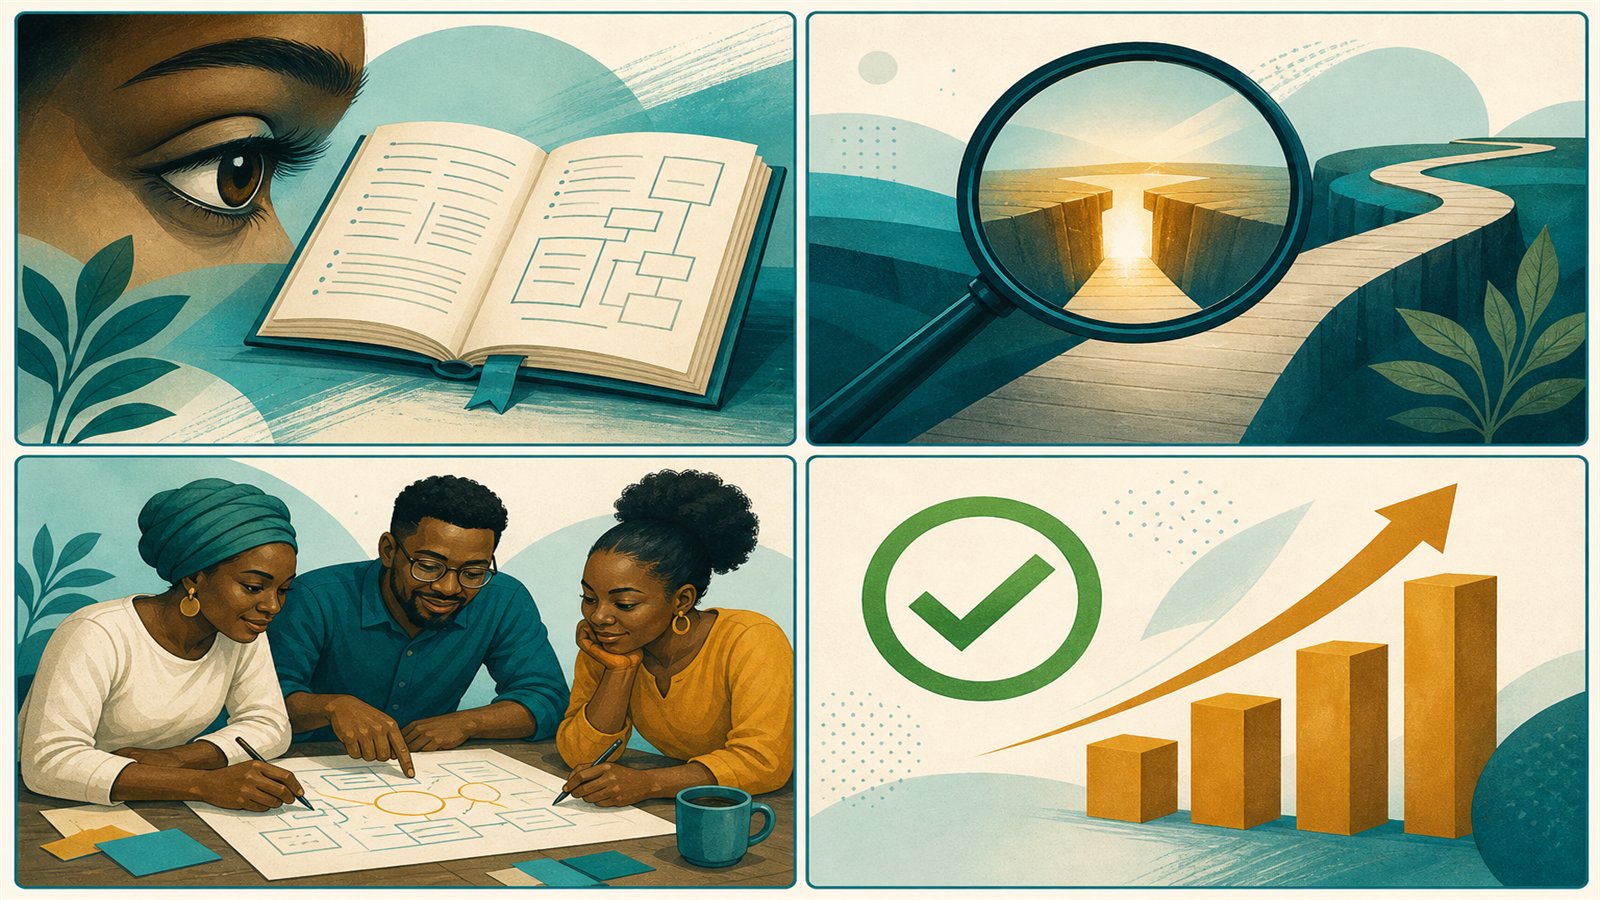
Watch the rules
Notice where laws, budgets, standards and institutional priorities are changing.
Find the gap
Identify what people and institutions still cannot do.
Build with people
Test the proposed solution with those who will use or experience it.
Prove the value
Show that the solution saves money, builds trust, expands opportunity or improves lives.
Founders and product teams: map the rule, the gap and the user workaround before you map the feature backlog.
Policymakers and civil servants: treat delivery capacity, budget, data, channels, trust, as part of the policy design, not an afterthought for implementers.
Investors: ask which permission, obligation, incentive, procurement path or infrastructure asset makes the demand durable, and what happens if it is delayed or captured.
Return to the Payment
Think again about that customer and that small business owner. The payment succeeded because a market had been cultivated, by rules that authorised the channel, by money that could settle safely, by technology that scaled trust, and by people who learned to use it in their own way.
Markets are not wild gardens that appear whenever two people want to trade. They are shaped spaces of rules, incentives, relationships and trust. Entrepreneurs who see only the product miss the stage. Policymakers who see only the rule miss the lived performance. The most useful work happens where both meet.
My argument is simple: build what people need, prove it works, and help policy scale it., Eric Omanga
When that happens, software becomes infrastructure, research becomes enterprise and policy becomes a market-making instrument.
Continue to Part II
What Kenya’s Post-Vision 2030 Blueprint Could Mean for Enterprise
Series: Real Business Is in Policy, apply the thesis to Kenya’s conversation beyond Vision 2030.
Also in this series: Part III
Coffee, Cash Crops and the Chief
Series: Real Business Is in Policy, when policy built the coffee market before the entrepreneur arrived.
Sources and further reading
- National Payment System Act, 2011 (Cap. 491A): Kenya Law
- National Payment System Regulations, 2014 (Legal Notice 109)
- Central Bank of Kenya: National Payments System overview
- GSMA: Mobile Money Regulatory Index 2021 (Kenya country note)
- Republic of Kenya / partners: National School Meals and Nutrition Strategy 2017-2022 (WFP document library)
- Kamau et al.: School Meals Case Study: Kenya (2024)
- Office of the Data Protection Commissioner: Data Protection Act, 2019
- ODPC: Guidance Note for Digital Credit Providers (2024)
From reading to civic action
Policy shapes markets and public value. Follow illustrative market challenges and accountability commitments that keep delivery visible.
Improve this article
Ask a question, suggest a correction, submit a source, share experience, or propose a topic. Contact details stay private. Publicly consequential allegations need editorial review.